Finance is one of the easiest functions to automate badly, because the cost of a mistake is immediate and visible: a wrong payment, a missed anomaly, a close that does not tie out. The teams that get this right automate the mechanical, repeatable steps and keep every approval and judgment call with a human. Here is how to tell the two apart.
What makes a finance task a good candidate for automation?
The same test applies here as anywhere else: the task should be repeatable, rule-based, and reversible or supervised if something goes wrong. Invoice data extraction is repeatable and rule-based. Deciding whether to approve a vendor's unusual payment term is not, it is a judgment call that depends on context an agent does not have. The line is not "does this involve money," almost everything in finance does. The line is "does this require a judgment call, or just consistent execution of a known process."
Which finance ops tasks should you automate first?
- Invoice data extraction and PO matching. Reading line items off an invoice and matching them to a purchase order is mechanical, and doing it by hand is where most AP teams lose the most time for the least value.
- Transaction reconciliation. Matching transactions across a bank feed, ledger, and invoices is rule-based pattern matching at volume, exactly what automation is good at.
- Recurring report generation. The monthly close packet, cash flow view, and burn rate report follow the same structure every cycle. Automating the assembly does not remove anyone's judgment, it removes the manual pull.
- Duplicate payment and anomaly flagging. Pattern detection against historical spend is something an agent can do continuously, catching things a monthly manual review would miss until it is too late.
Which finance ops tasks should stay with a human?
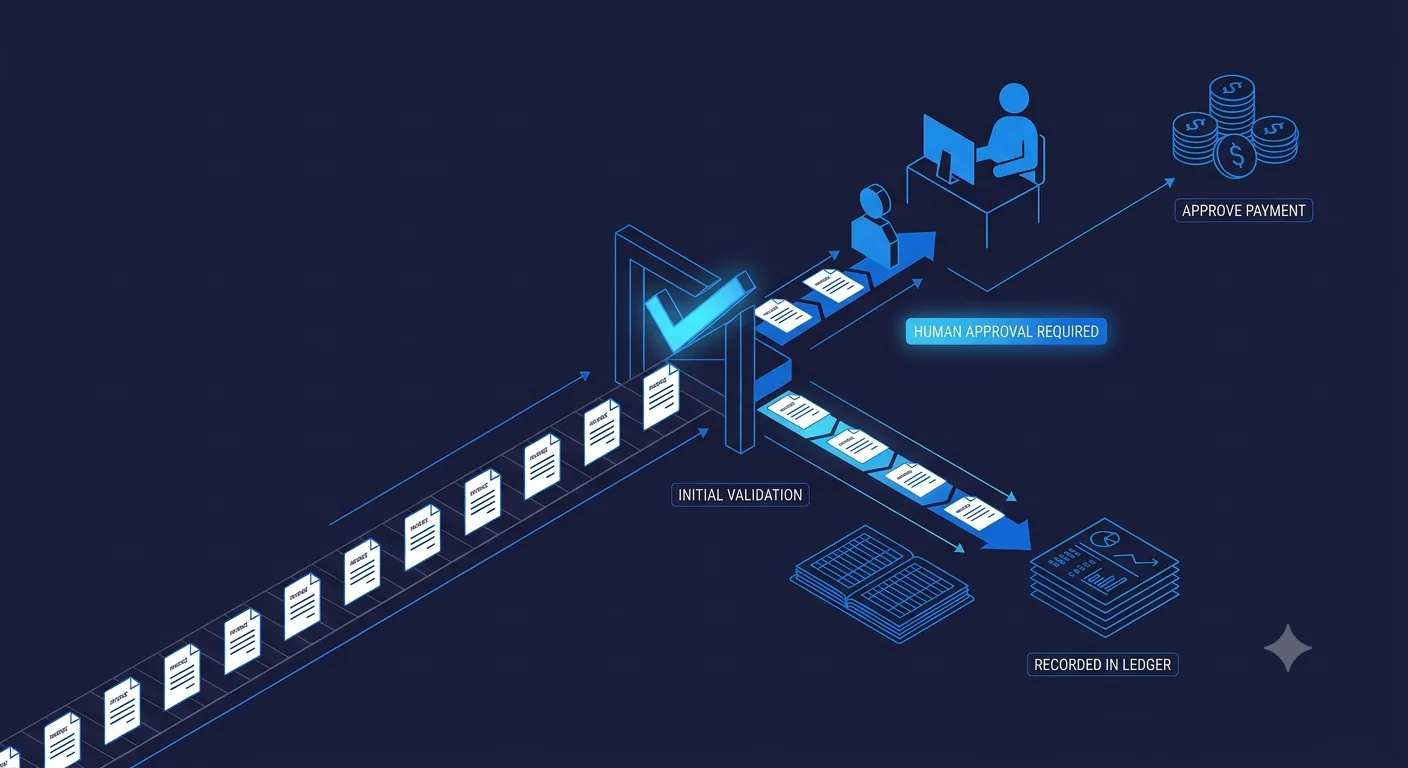
- Payment approval. The agent can prepare and recommend, but the actual authorization to move money should sit with a person, every time, no exceptions.
- Vendor negotiation and unusual payment terms. Context and relationship judgment that does not reduce to a rule.
- Forecasting and board reporting narrative. The numbers can be pulled automatically; the interpretation and the story around them is a human job.
- Anything flagged as an anomaly. The agent's job is to flag it fast, not to decide unilaterally whether it is actually a problem.
Is it actually safe to let an agent touch reconciliation and invoicing?
It is safe when the agent's role is proposing and flagging rather than executing unsupervised. A well-built finance agent sits upstream of your existing approval chain, it does not replace it. Matches get proposed and a human confirms, payments get queued and a human authorizes, anomalies get surfaced and a human decides. The risk profile looks more like a very fast, very consistent junior analyst than an autonomous system with payment authority, and it should be built that way deliberately, not by accident.
How much faster does a close actually get?
The honest answer depends on your current process maturity more than on the tool. Teams doing reconciliation manually in spreadsheets see the largest jump, because the manual-matching step is usually the single biggest time sink in a monthly close. Teams already on a modern accounting stack with decent automation see a smaller, still meaningful, improvement concentrated in anomaly detection and reporting rather than in the matching itself.
How do you roll this out without creating a new risk?
Start on one ledger or one entity, not your whole finance stack at once. Run the agent's proposed matches alongside your existing manual process for a full close cycle before trusting it to run ahead of a human review. Keep payment authorization with a person from day one, regardless of how well the earlier steps perform, that boundary should not move based on a good first month.
If you want this scoped against your actual close process and accounting system, see our AI agent for finance ops for the workflow and integrations, or talk to us directly.